Embassy Discuss a decisionDiscuss
Visitors standing in a vast room lit by a low orange sun

Embassy · Due diligence advisory

Due diligence on the people who will carry the deal.

Independent leadership and governance due diligence for family offices, private equity and boards. Before capital is committed, Embassy tests who actually decides, whose incentives diverge, and whether the relationships the plan depends on will transfer.

Confidential · Led by John Wolf · Written brief in seven to ten business days

What diligence usually misses

The decision is carrying more than the model.

Financial, legal, tax and commercial diligence examine the asset and the transaction: whether the numbers, contracts and systems hold. Assessment firms score each executive one at a time.

What sits between those people is examined far less often: who decides, who defers, and whose customers follow whom. It is where plans slip after closing.

Embassy’s due diligence examines that layer. It complements the other disciplines and replaces none of them.

The decisions it is built for

01 · What Embassy examines

Four things that decide whether the plan survives closing.

Each is tested against the record. Every claim in the brief is marked observed, inferred or unresolved, with its source.

Authority

Who actually decides after closing.

The documents name a chief executive. The largest customers still call the founder. An undefined approval right in the shareholder agreement decides which of those is true.

Incentives

Whose incentives quietly diverge.

The founder’s rollover, the new chief executive’s vesting, the head of sales with no retention arrangement, and the buyer’s own reluctance to arbitrate between them.

Relationships

Whether the relationships transfer.

Customers, lenders and regulators deal with people. Renewal dates and change-of-control clauses show when you will find out who they were dealing with.

The counter-case

The strongest case against the thesis.

Written down before commitment, with the conditions under which the thesis holds and the questions that must be answered first.

The cost

Investors report that the people side is where plans slip, and that they act on it late.

71%of large US buyouts hired a new chief executive under private equity ownership.Gompers, Kaplan & Mukharlyamov, HBS / NBER, 2022
92%of private equity professionals say waiting too long on talent issues led to portfolio underperformance.Bain & Company, Global Private Equity Report, 2021
1 in 3failed joint ventures, by one estimate, trace problems partly to boards that did not keep decision rights clear.Boston Consulting Group, 2026

02 · How it differs

What other due diligence covers, and what it leaves open.

Each of these providers does valuable work. Embassy covers the layer between them, and works alongside all four.

Executive search firmsAssessment psychologistsInvestigative firmsHuman-capital consultantsEmbassy
ExaminesExecutives against the marketEach executive’s capability and personalityIntegrity, litigation, reputationPay, benefits, retention, cultureAuthority, incentives and relationships between the principals
Unit of analysisThe individualThe individual, often gradedThe individual or entityThe workforceThe decision and the people carrying it
OutputReferences, benchmarks, replacement optionsIndividual reports and a talent planFindings on records and conductLiabilities and retention plansClaims and evidence, counter-case, conditions for commitment
Strongest atMarket knowledge and candidate benchesDepth on one personBackground and recordsCompensation and HR liabilitiesWhether the plan’s human conditions hold
A faceted stone figure with crystal geodes breaking through its surface

01 · The relationships

Between the people, not only about them.

Assessment firms score executives one at a time. Embassy maps what sits between them: stated and actual decision rights, the founder’s continuing reach, and which customer relationships depend on whom.
02 · The evidence standard

Every claim marked observed, inferred or unresolved.

The investigative standard, applied to people and governance. Each finding carries its source and a confidence level, and the brief sets out the strongest case against the thesis.

03 · Senior-led

The person you speak to does the work.

John Wolf leads every engagement, from the first conversation to the debrief. The interviews, the reading of the record and the brief are his.

03 · The deliverable

The Decision Diligence Brief.

Pages from an illustrative composite: a family office buying control of a founder-led logistics company, where the founder becomes executive chair and the chief operating officer becomes chief executive.

ObservationInferenceCounter-caseUnresolvedClient judgment
Illustrative composite — not a client case

The thesis holds on operations and is unproven on customers.

Three of the five largest accounts, 34% of revenue, were won and are still managed by the founder, who becomes executive chair at closing. The draft shareholder agreement gives the chair approval over “material commercial terms”, which it does not define.

  1. Operating discipline is the COO’s, on documentary evidence. C1 · High confidence
  2. Founder-held accounts are 34% of revenue; one requires consent on change of control. C2, C6 · High
  3. Chair approval rights are undefined and overlap the chief executive’s. C5 · High
  4. 40% of planned year-one growth depends on contracts the founder is introducing. C7 · Medium

What would change this view: a signed chair remit that excludes the three accounts, and a customer-by-customer transition plan agreed by founder and chief executive.

One page for the committee

The top findings, each tied to a claim and a confidence level, and the one line that says what would change the view.

Request the full sample brief
Illustrative composite — not a client case
IDClaimWhat the record showsStatus
C1The COO built the operating discipline.Margins and on-time delivery improved across the COO’s tenure; operating reviews are COO-authored.Observed
C2Customer relationships sit with the company.Three of the top five accounts were won by the founder, who remains named contact.Contradicted in part
C3The founder is ready to step back.Written endorsement of the succession; also proposed chairing a new “commercial committee”.Inferred
C5The chief executive will hold commercial authority.Shareholder agreement §7.2: chair approval over “material commercial terms”, undefined.Unresolved

Evidence before opinion

Each claim in the investment thesis is set against what the record shows, with its status and sources. Single-source claims are marked as such.

Illustrative composite — not a client case
DecisionStated ownerObserved ownerGap
Pricing on the three largest accountsChief executiveFounder approvesYes
New regional contractsChief executive; board above thresholdFounder introduces and negotiatesYes
Operating budgetChief executiveCOO, the incoming chief executiveNo
Chair and chief executive disagreeBoardNo independent director; buyer prefers not to arbitrateYes

Stated and observed

Who the documents say decides, set against who decides on the record and in the conversations. The gaps are where a plan stalls after closing.

Illustrative composite — not a client case
Before signingOwnerEvidence of completion
“Material commercial terms” definedBoth parties’ counselRevised §7.2
Transition plan for the three accountsFounder and chief executiveSigned plan, dates per account
Consent route for the largest accountBuyer’s counselCustomer correspondence
ProceedPauseReviseDecline

Each path is tied to conditions and claim IDs. The choice belongs to the investment committee.

Conditions, not a verdict

What must be true before signing and in the first 100 days, with an owner and evidence of completion for each. The brief never makes the investment decision.

04 · The engagement

Seven to ten business days, from scope to debrief.

Scoped after a short fit conversation, between letter of intent and signing. John Wolf leads every engagement.

You provide

The materials already in the data room

One interview with the deal lead

Consent for up to three stakeholder conversations

Embassy works
Decision, scope and conflicts confirmedDays 1–2
Record review and sponsor interviewDays 2–5
Consented stakeholder conversationsDays 4–7
Evidence map, counter-case, conditionsDays 6–9
Written brief and executive debriefDays 7–10
You receive

A one-page executive summary

Claims and evidence, with confidence levels

Red flags by severity

Decision rights, stated and observed

Incentives by party, the buyer’s included

The counter-case

Conditions before signing and for the first 100 days

A sixty-minute debrief

The engagement ends with the brief and the debrief. Monitoring, implementation or negotiation support would each be a separate scope.

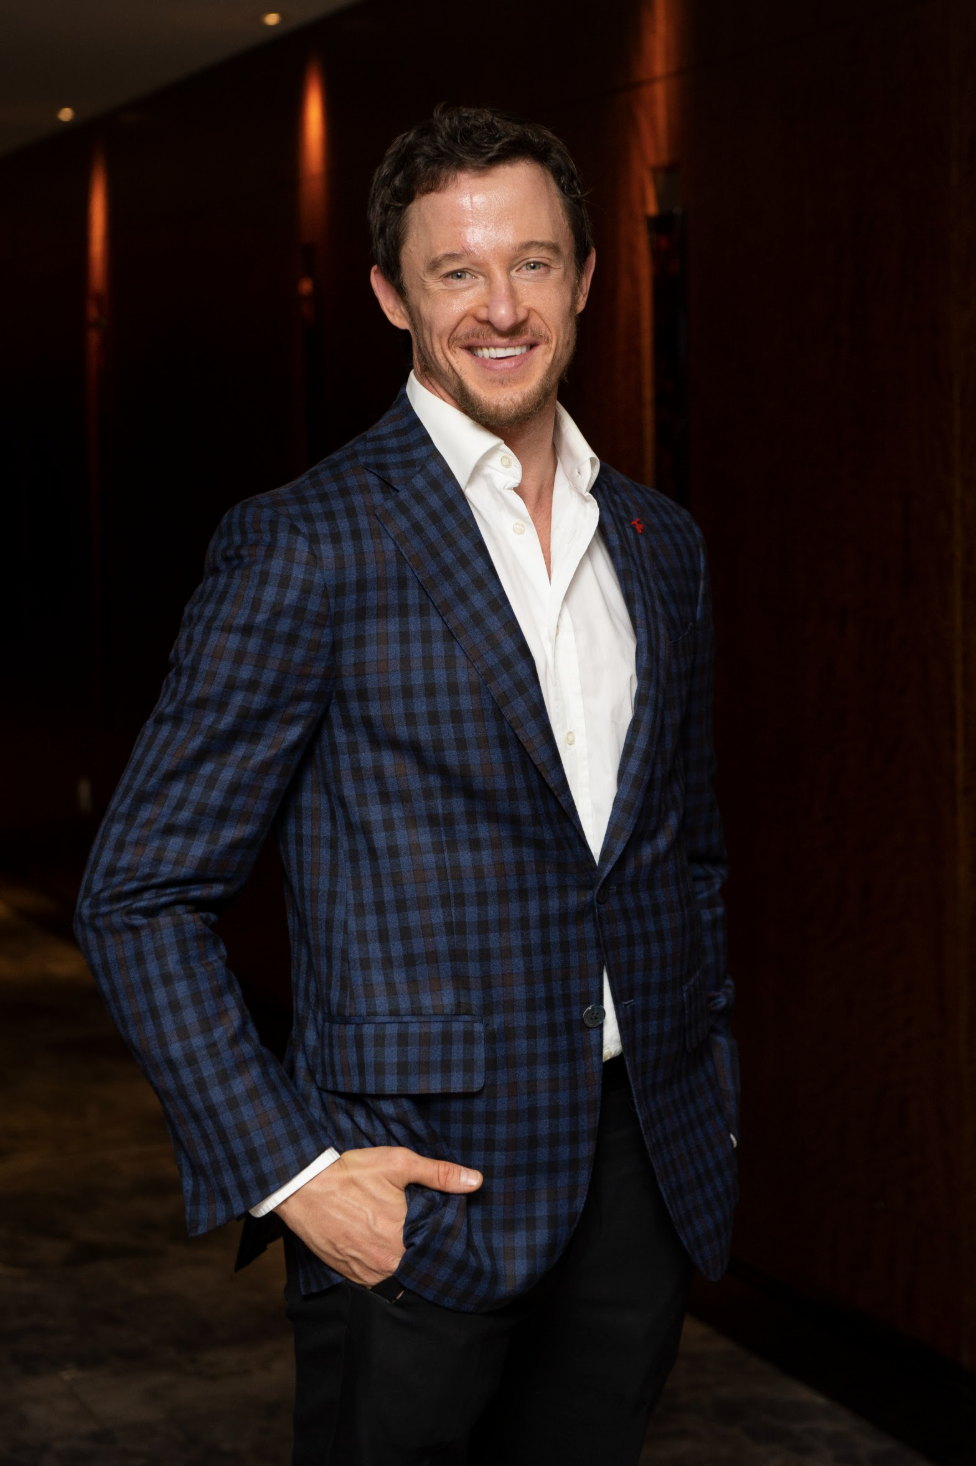
John Wolf
John Wolf standing before a James Turrell light oval

05 · Who leads it

John Wolf.

John Wolf leads every engagement personally. Twenty years operating where outcomes depended on human judgment, across private capital, family offices, founder transitions, transaction readiness, AI infrastructure and relationship-sensitive negotiations.

Why John Wolf, why Embassy →

06 · Scope and questions

Before you write.

  • Complements financial, legal, tax, commercial, technical, investigative and regulated investment diligence.
  • Does not certify an investment, predict behavior or diagnose personalities.
  • Begins with a conflict and confidentiality check. No confidential documents through this page.
  • Not for routine hires, background screening on its own, or decisions already signed.
What kinds of decisions fit?

Private-market decisions whose success depends on particular people holding particular roles: founder transitions, investments that rely on the team in place, partnerships with unclear authority, roll-ups that need their operators, and recapitalizations that change governance.

When should Embassy become involved?

Between letter of intent and signing, while the findings can still shape terms, structure or timing.

What information is required?

The materials you already hold, one interview with the deal lead and, where scoped, consent for up to three stakeholder conversations. Nothing is requested before terms are in place.

Does this replace management assessment or background checks?

No. It examines a different layer. Where individual assessment or background screening is needed, the brief is written to be read alongside it.

How are stakeholder conversations handled?

Only with each person’s consent and within the agreed scope. Each person knows why they are being asked and how their words will be used.

How is confidentiality protected?

Every engagement begins with a conflict check and written confidentiality terms. Materials are shared only after those terms are agreed.

How is the fee set?

Scoped after a short fit conversation and agreed in writing before work begins.

What happens after the brief?

The engagement ends. Any further work, such as monitoring or implementation, is scoped separately if you want it.

Two ways to begin.

For a live decision

An active transaction, appointment, partnership or transition. John replies personally within one business day.

Confidential. Please leave out deal specifics; terms come first.

To see the deliverable first

The full illustrative sample brief, sent to your work email. A composite, not a client case.